
What if the lowest monthly payment costs more over time? When an aging AC struggles, replacement can feel urgent, and spreading out the expense may seem like the easiest path. A search for “financing for new air conditioner Orlando” homeowners can consider often starts with one question: what will I pay each month? That matters, but it’s only part of the picture. Interest, loan term, fees, promotional-period rules, and system efficiency can all affect the overall cost.
Compare financing options alongside the proposed equipment and installation, not in isolation. This guide explains common financing structures, the terms to review, and practical ways to assess a replacement proposal so you can weigh the full cost rather than choose by payment alone.
You’ll also learn how system sizing and efficiency factor into ownership costs in Orlando and what to consider before deciding. Whether you’re in Orlando, Oviedo, Winter Springs, Winter Park, or Altamonte Springs, a clear comparison can help you make a confident replacement decision for your home.
Key Takeaways
- Understand how contractor-arranged plans, personal loans, and home-equity borrowing differ, while recognizing that terms and eligibility vary.
- Compare financing for new air conditioner Orlando offers by APR, total repayment, fees, loan term, and late-payment consequences, not just the monthly amount.
- Review deferred-interest terms carefully so you know whether unpaid balances could accrue interest under the agreement.
- Use a pre-application checklist to assess your AC needs, set a manageable budget, and review written terms before deciding.
- Consider the installation plan and the system’s fit for your home alongside the financing when choosing a replacement.
Financing a New Air Conditioner in Orlando: What to Decide First
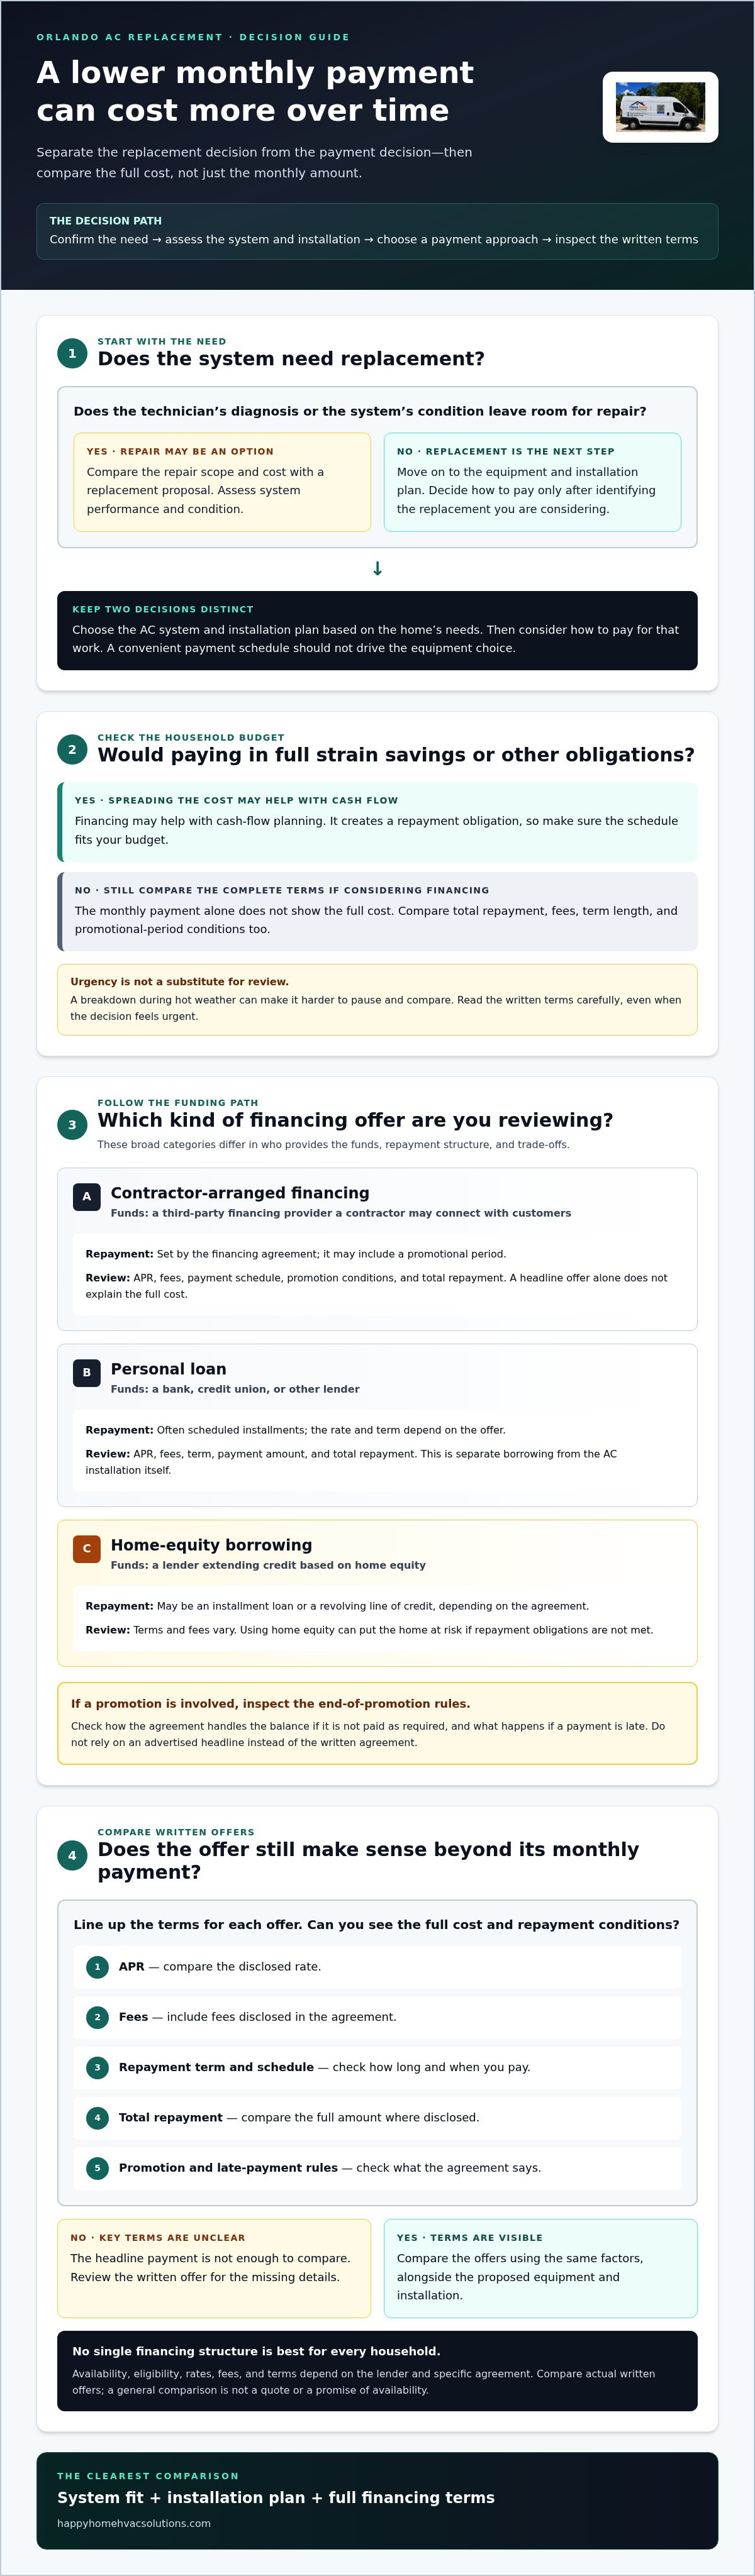
When an AC falters in Central Florida heat, the pressure to restore comfort can make replacement feel like a decision you need to make all at once. A clearer process separates three questions: Does the system need replacement? What equipment and installation suit the home? And what payment approach fits the household budget?
AC financing is borrowing or a payment arrangement that spreads the cost of a replacement over time. It addresses how you pay, not whether a particular system is right for your home. Equipment suitability and installation quality matter to dependable comfort, too. For a foundational overview of how Heating, ventilation, and air conditioning (HVAC) systems serve a home, see the linked reference.
If you’re researching “financing for new air conditioner Orlando” homeowners may consider, first establish whether replacement is the right next step. If a technician’s diagnosis or the system’s condition leaves room for repair, compare the repair scope and cost with a replacement proposal. Assess the system’s performance and condition, then consider payment options for the replacement you’re actually considering.
When financing may help with an Orlando AC replacement
Spreading a large household expense over time may help with cash-flow planning, especially if paying the full amount at once would strain savings or affect other obligations. A breakdown during hot weather can make it harder to pause and compare, so read the written terms carefully even when the decision feels urgent. Financing creates a repayment obligation, so make sure the schedule fits your budget.
Why the monthly payment is only part of the decision
A lower monthly payment can come with a longer repayment period, so it doesn’t show the full cost. Compare total repayment, fees, term length, and promotional-period conditions as well as the payment amount. Check how the agreement handles the end of a promotion and what happens if a payment is late. The right structure depends on your budget and circumstances; there’s no single best option for every household.
Keep the two decisions distinct: choose an AC system and installation plan based on the home’s needs, then consider how to pay for that work. This helps prevent a convenient payment schedule from driving the choice of equipment. Next, compare common financing categories and the trade-offs their terms may involve.
Common Ways to Finance a New Air Conditioner, and How They Differ
Homeowners comparing financing for new air conditioner Orlando options may encounter three broad categories: contractor-arranged plans, personal loans, and borrowing that uses home equity. These options aren’t interchangeable. The source of funds, repayment schedule, fees, and financial consequences can differ substantially.
Availability, eligibility, rates, fees, and terms depend on the lender and the specific agreement. The table is a general guide, not a quote or a promise that any option will be available to every homeowner. Compare actual written offers using the terms disclosed in each agreement.
| Option | Who provides the funds | Typical repayment structure | Key trade-offs to review |
|---|---|---|---|
| Contractor-arranged financing | A third-party financing provider, which a contractor may connect with customers | Set by the financing agreement; may include a promotional period | Review the APR, fees, payment schedule, promotion conditions, and total repayment. A headline offer alone doesn’t explain the full cost. |
| Personal loan | A bank, credit union, or other lender | Often repaid in scheduled installments; the rate and term depend on the offer | Compare APR, fees, term, payment amount, and total repayment. It’s separate borrowing from the AC installation itself. |
| Home-equity borrowing | A lender extending credit based on home equity | May be an installment loan or a revolving line of credit, depending on the agreement | Terms and fees vary, and using home equity can put the home at risk if the borrower doesn’t meet repayment obligations. |
Contractor-arranged financing and promotional offers
A contractor may connect customers with a third-party financing provider, but the lender sets the financing agreement and its terms. Promotional periods can include conditions that affect what you owe, including how the balance is handled if it isn’t paid as required. Review the written agreement for the APR, fees, payment schedule, and promotion-end rules rather than relying on an advertised headline.
Personal loans and home-equity borrowing
A personal loan is separate borrowing and may have fixed repayment terms. Home-equity borrowing uses equity in the property and may be secured by the home. That distinction matters: failure to repay secured borrowing can put the home at risk. Suitability depends on your finances, lender terms, and individual circumstances, so compare the obligations, not just the initial payment.
What the comparison table should make easy to see
For each written offer, line up the APR, fees, repayment term, payment schedule, and total repayment where disclosed. The Consumer Financial Protection Bureau offers consumer-finance education on borrowing and loan terms; lender-specific eligibility and agreement details still determine the terms of a particular offer. Keeping general guidance separate from the actual agreement makes comparison clearer.
Once you’ve considered how you might pay, focus on the separate equipment decision: a properly planned replacement starts with the home’s comfort needs. Happy Home HVAC Solutions is a family-owned, licensed HVAC company serving Orlando and nearby Central Florida communities. Learn about AC installation in Orlando as you plan the replacement itself.
How to Compare AC Financing Offers Beyond the Monthly Payment
A monthly payment is easy to spot, but it doesn’t show the full cost of borrowing. A lower monthly payment can result from a longer repayment term, not necessarily a lower total cost. To compare financing for new air conditioner Orlando offers fairly, review each written agreement and check that proposals cover comparable equipment and installation work.
Read the agreement for the full cost and conditions
Use this checklist for each offer:
- APR: Check the annual percentage rate and when it applies.
- Total repayment: Review the total amount due over the full term, where disclosed.
- Fees and term: Note any fees and how long payments continue.
- Payment schedule: Confirm when payments begin, their frequency, and the amount due.
- Missed payments: Understand any late charges, rate changes, or other consequences described in the agreement.
- Promotional period: Identify when it ends and what happens to any remaining balance.
Pay close attention to the difference between deferred interest and a period with no interest charged. With deferred interest, the agreement may allow interest to accrue during the promotion and become payable if the required balance isn’t cleared by the deadline. A no-interest introductory period generally means interest isn’t charged during that period, though a rate may apply afterward. The wording and consequences depend on the specific agreement, so read its terms rather than relying on an offer’s headline.
Compare the equipment and installation scope too
Financing offers are difficult to compare if they cover different work. Check whether each proposal specifies comparable equipment and installation scope, including system sizing, efficiency, warranty terms, and included services. A lower financed amount may reflect a different system or less work, not a better deal for the same replacement.
Keep the equipment decision separate from the borrowing decision. First understand what system and installation the home needs; then compare how each financing agreement affects total repayment and the household budget. For more context on replacement planning, see the AC replacement cost guide for Orlando.
Write the terms side by side before deciding. If a key detail, such as total repayment or what happens when a promotional payoff deadline is missed, isn’t clear in the documents, don’t assume the most favorable interpretation. The agreement’s written terms are what matter.
A Practical Orlando Homeowner Checklist Before Applying
Preparation can make an AC replacement feel more manageable, even if the current system is struggling in Orlando’s heat. Before applying for financing for new air conditioner Orlando homeowners are considering, work through the decision in order: assess the system, set a comfortable budget, compare written terms, review the paperwork, then decide.
- Assess the system: Understand whether repair or replacement is being considered and what the proposed replacement includes.
- Set a household budget: Consider a payment that fits alongside regular expenses, not just the amount a lender might approve.
- Compare written terms: Review each proposal and financing agreement using the same equipment and installation scope where possible.
- Review before committing: Check the payment schedule, term, fees, warranty coverage, and cancellation conditions.
- Decide with the full picture: Proceed only when the system, installation, and repayment terms make sense for your circumstances.
Set a budget that considers the whole household
Think beyond the monthly payment. Leave room in your household budget for regular expenses and consider ownership factors such as maintenance, warranty coverage, and future energy use. Orlando’s cooling demands make system operation an important part of the long-term picture, but no efficiency label guarantees a specific energy bill or savings. Warranty coverage varies, so read what’s covered, for how long, and under what conditions. For more context, see this Florida HVAC warranty guide.
Match the replacement system to the home
System capacity should suit the home rather than being chosen by size or a prominent efficiency rating alone. HVAC professionals use load calculations to help determine appropriate capacity based on the home and its characteristics. In Florida’s heat and humidity, correct system selection supports dependable comfort. A larger unit or higher efficiency rating isn’t automatically the best fit; compare the proposed system and installation as a whole.
Review application and contract details before committing
The lender determines approval decisions and the information required for an application. Follow its current instructions and read the written disclosures alongside the AC proposal. Confirm payment dates, repayment term, fees, and cancellation conditions before signing. Keep copies of the proposal, financing agreement, and warranty documents together for easy reference.
For a replacement plan built around your home’s comfort needs, explore professional AC installation in Orlando.
Plan Your New AC Installation in Orlando with Confidence
Financing is only one part of a replacement decision. The system must suit your home, the installation plan should be clear, and the agreement should fit your budget. Consider these pieces together instead of letting the monthly payment drive the equipment choice.
Happy Home HVAC Solutions is a family-owned, licensed HVAC company serving Orlando and nearby Central Florida communities. As an LG-certified HVAC contractor, Happy Home plans AC installations around the home’s comfort needs. This gives you a clear starting point for discussing the replacement itself, separate from any financing decision or lender’s approval process.
What a careful installation plan should address
A useful proposal should explain the home’s cooling requirements, the recommended system capacity, and the work included in the installation. It should also give you room to ask questions about equipment, efficiency, and project scope before deciding. Clear details make financing offers easier to compare fairly because you can see whether different payment proposals cover the same system and installation work.
Performance expectations should be tied to the proposed equipment and the home. A particular efficiency rating alone can’t promise a specific energy bill or level of comfort. Understanding why a system is recommended helps you assess whether the proposal addresses your household’s needs.
Understand warranty coverage as part of long-term value
Warranty coverage is part of the ownership picture, alongside financing terms and installation scope. Happy Home offers up to a 12-year warranty on many installations, but duration and coverage depend on the installation and applicable terms. Review the specific documentation to understand what applies to your system. For more background, read this guide to a 12-year HVAC warranty in Florida.
Take the next step without rushing the decision
Before committing, compare written financing terms, make sure you understand the proposed system and installation, and take the time you need to decide. If questions remain about the replacement plan, a conversation about your home’s AC installation can clarify the equipment and work being proposed. You can discuss installation details separately from financing approval or a decision to borrow.
Talk with Happy Home about your AC installation.
Choose Your Next AC Step with Confidence
A sound replacement decision looks beyond the monthly payment. Compare APR, fees, repayment term, and total cost, then make sure each offer covers a similar system and installation scope. Choose equipment suited to your home and review the agreement carefully before committing. With a clear process, financing for new air conditioner Orlando homeowners are considering can be evaluated as part of the larger comfort and ownership decision.
As an LG-certified HVAC contractor, the team installs AC systems and offers up to a 12-year warranty on many installations, subject to applicable coverage terms. A conversation about your home’s installation needs can clarify the system and work being proposed, while financing decisions remain between you and the relevant lender.
Talk with Happy Home about your Orlando AC installation. Compare the details and move forward when the plan feels right for your home.
Frequently Asked Questions
What financing options are available for a new air conditioner in Orlando?
Common options include contractor-arranged plans through a third-party financing provider, personal loans, and home-equity borrowing. Each works differently, and availability, eligibility, fees, rates, and repayment terms depend on the lender and agreement. As you compare financing for new air conditioner Orlando offers, look beyond the payment amount and compare total repayment and contract conditions. These options may be relevant to homeowners in Orlando, Oviedo, Winter Springs, Winter Park, and Altamonte Springs.
How much does it cost to finance a new air conditioner in Orlando?
The financing cost depends on the replacement proposal and the specific loan or payment agreement, so there isn’t one amount that applies to every home. To understand your total obligation, review the amount financed, APR, fees, repayment term, payment schedule, and total repayment where disclosed. Check what equipment and installation work the proposal includes, too. Comparing written offers with the same project scope gives you a clearer picture than comparing monthly payments alone.
Can I finance a new AC with bad credit?
Possibly, but approval and terms depend on the lender’s criteria and your individual application. A lender may consider information such as credit history and other application details, but requirements vary, and approval isn’t guaranteed. Review the lender’s current application instructions and written offer before deciding. If an offer is available, compare its APR, fees, repayment schedule, and total cost with your household budget rather than focusing only on whether you qualify.
Is 0% financing for an air conditioner really interest-free?
It depends on the agreement. A true no-interest period means interest isn’t charged during the stated period, though a rate may apply afterward. Deferred interest is different: interest may accrue during the promotion and become payable if the balance isn’t paid as required by the deadline. Read the written terms for the promotional end date, payment requirements, and treatment of any remaining balance. Don’t rely on an advertised “0%” label alone.
How do I compare AC financing offers?
Compare APR, total repayment, fees, term length, payment dates, and late-payment consequences. Check promotional terms, too, including what happens if a balance remains when the offer ends. Then make sure each financing offer relates to a comparable AC system and installation scope. A longer repayment term may lower the monthly payment without lowering the overall cost. Use the written agreements to compare the complete obligation, not just the first number you see.
Should I repair my AC or finance a replacement?
Base the choice on the system’s condition and a professional assessment, not on financing alone. If repair remains a reasonable option, compare its scope with a replacement proposal before deciding. For a replacement, consider whether the recommended system suits your home and whether the installation work is clearly described. In Orlando-area heat, including nearby Winter Park and Oviedo, comfort matters, but the right choice depends on your equipment, home, and budget.
Does financing a new AC include installation and warranty coverage?
Not automatically. The financed amount and included work depend on the written proposal and financing agreement, so check whether installation is included and what the scope covers. Warranty coverage is separate from loan repayment and depends on the equipment, installation, and applicable terms. Happy Home HVAC Solutions is a licensed, LG-certified HVAC company serving Central Florida, including Orlando and nearby communities, and offers up to a 12-year warranty on many installations. Review the specific warranty documents for coverage details.


